Time in business
Around six months of operating deposits is a common starting conversation.
Home · Industries · Retail
Industry
Storefronts and omnichannel shops purchase before demand proves out — capital should match the season, not hope for it.
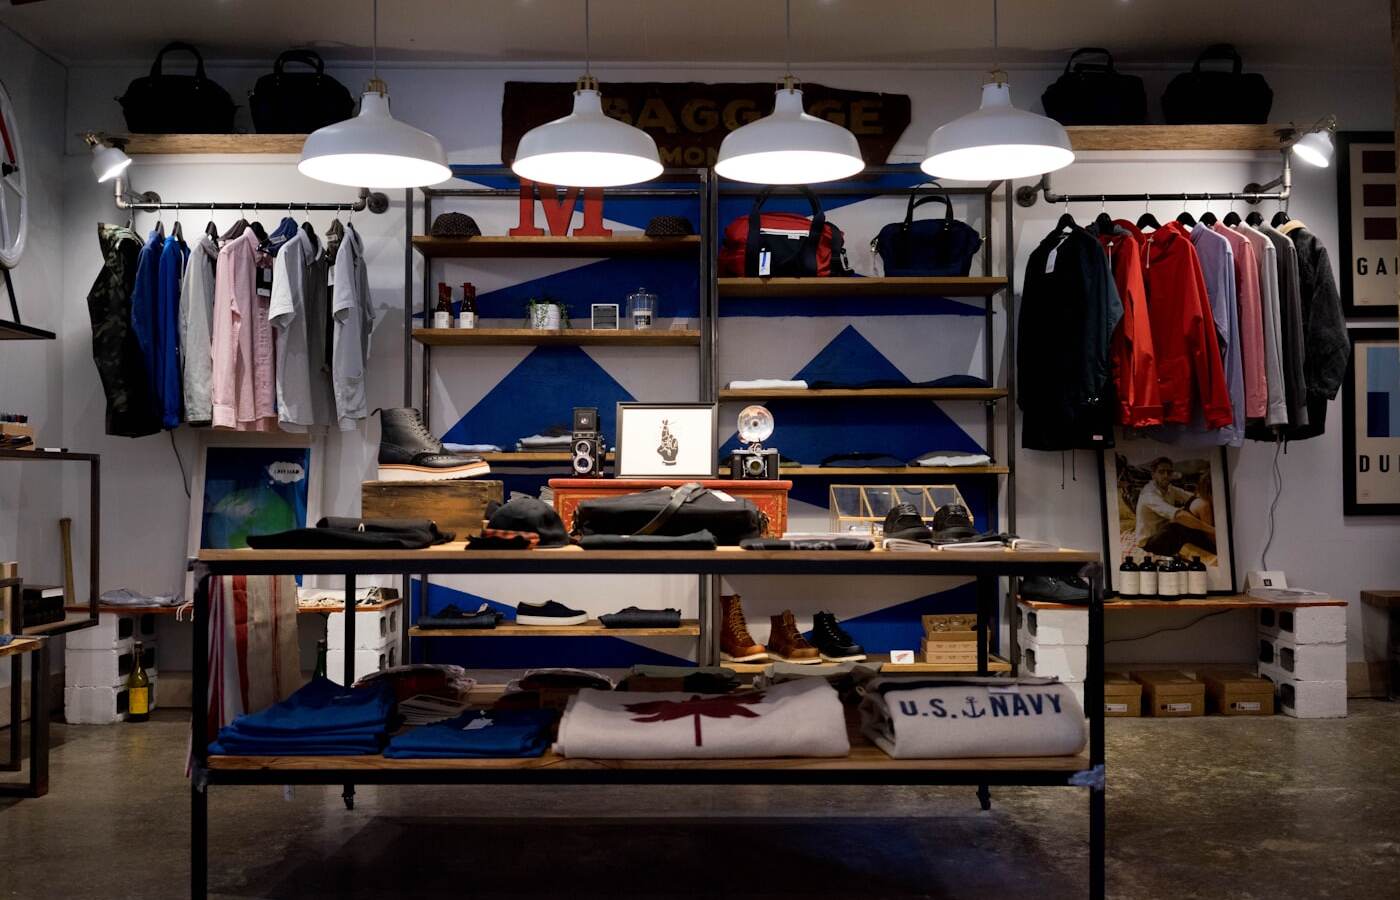
Vendor terms, ad spend, and returns create spikes. Lines and short-term notes bridge the gap when statements show a pattern, not a one-off weekend.
We read deposit consistency, returns and chargebacks, and whether existing card advances already claim a slice of every batch. A one-time seasonal buy is a different file from a permanent margin problem.
Structures we often discuss
Eligibility snapshot
Around six months of operating deposits is a common starting conversation.
Around $15,000 in monthly sales is a common starting point. Pure online concepts still need a clean deposit history.
Personal credit near 500+ is often discussed, along with existing obligations in the trade.
Inventory that never turns, landlord arrears, and stacked advances. Say what the capital buys and when you expect it back in the register.
Soft inquiry to start. Applying is free and is not an offer of credit.